Table of Contents
- Why Installation Insurance Is Non-Negotiable for Sign Projects
- The Real Risk: What Happens Without Proper Coverage
- Our Comprehensive Insurance and Bonding Approach
- Understanding Workers Compensation and Your Protection
- How Our Coverage Limits Safeguard Your Investment
- The Permit Process: How Insurance Integrates Into Compliance
- Why General Contractors Choose Our Verified Coverage
- Documentation and Peace of Mind: What You Receive
- Our 5-Year Warranty Works Hand-in-Hand With Insurance
- Getting Started: Requesting Your Proof of Coverage
- Frequently Asked Questions (FAQ)
Why Installation Insurance Is Non-Negotiable for Sign Projects
When you’re planning a storefront renovation or upgrading your facility’s exterior branding, the sign installation itself might feel like the straightforward part. But here’s what separates responsible contractors from risky ones: proof of proper insurance coverage before the first drill hits the wall. We’ve installed hundreds of commercial signs across the Dallas area, and we’ve seen what happens when businesses skip this critical step.
Installation insurance and bonding aren’t paperwork hurdles. They’re your legal shield and your financial protection rolled into one.
Commercial sign installation involves working at height, heavy equipment, electrical connections, and structural modifications to your building. Each of these elements carries real liability exposure. If something goes wrong during installation, your business could face property damage claims, worker injury lawsuits, or third-party injury claims that balloon into six or seven figures.
Here’s the practical reality: most commercial property insurance policies don’t cover injury or damage that occurs during the installation process itself. That gap is where installation liability insurance steps in. We carry comprehensive coverage because our clients depend on it, and Dallas city permits often require it as a condition of approval.
Think of it this way. A sign falls during installation and damages a neighboring storefront. Without proper liability coverage, your sign company (or worse, you as the property owner) would pay out of pocket. That single incident could exceed $50,000 to $100,000 in repairs and legal fees.
What to do next: Ask any sign contractor for a Certificate of Insurance before signing a contract. Don’t accept verbal promises or “we’ll get that to you later.” It’s a red flag if they hesitate.
The Real Risk: What Happens Without Proper Coverage
We talk to business owners regularly who’ve hired cut-rate contractors to save a few thousand dollars on signage. The contractors show up, install the sign quickly, and disappear. Then something happens: a worker gets injured, the installation damages the storefront entrance, or the sign itself fails because poor technique was used.
Now your business is liable. Your insurance company may deny the claim because you hired an uninsured contractor. You’re personally responsible for legal defense and settlements. Suddenly that $2,000 savings on installation costs you $75,000 in claims and legal fees.
We’ve also seen situations where uninsured contractors cut corners on structural assessment. A sign gets installed on a deteriorating wall section or an inadequate mounting point. Months later, weather stress causes failure. If no proper installation records exist and no liability coverage was in place, the building owner assumes all responsibility.
General contractors face their own exposure when they hire subcontractors without verifying coverage. If a sign installer’s uninsured worker gets hurt, that worker might sue the general contractor directly. Your proof of insurance protects everyone in the chain.
Actionable takeaway: Review your current contractor agreements. If you don’t have signed proof of insurance on file for every subcontractor, reach out today and collect it. Document everything before work starts.
Our Comprehensive Insurance and Bonding Approach
We maintain general liability coverage of $1 million per occurrence and $2 million aggregate, which is standard for commercial installation work but significantly higher than many local competitors operate. We also carry completed operations coverage, which means our liability protection extends beyond the installation date if issues emerge later.

Additionally, we maintain a performance bond. This protects you and your business if we fail to complete the project as agreed or if our work doesn’t meet contractual specifications. The bond ensures that if we default, a third party compensates you rather than leaving you stranded.
Our workers compensation insurance covers all our installation technicians and fabrication staff. This is not optional in Texas; it’s a legal requirement. We’ve never cut corners here because injured workers deserve protection and your business deserves to know that claim liability is properly handled.
Every Certificate of Insurance we issue is current, verified by our insurance broker, and delivered before any work begins. You’ll have our agent’s direct contact information so you can independently verify our coverage if needed.
Next step: When you request a quote from us, ask for our Certificate of Insurance to be included with the proposal. It’s a standard part of our process.
Understanding Workers Compensation and Your Protection
Texas allows businesses to opt out of workers compensation insurance under specific conditions, but we choose full coverage because our team is our greatest asset. When a technician is injured installing your sign, workers comp covers their medical expenses and lost wages without requiring you to be sued.
Here’s why this matters to you as a business owner: if we didn’t carry workers comp and one of our installers got hurt on your property, they could sue you directly for damages. That’s a major liability exposure. With proper coverage in place, the claim goes through the workers comp system, and your business is protected.
The coverage also includes occupational disease claims, so if a technician develops an illness related to their work over time, it’s handled through the same protective mechanism. You won’t receive a surprise liability claim years later.
Our installation teams are trained and safety-certified. We maintain incident logs and safety protocols. Combined with full workers compensation coverage, this means your project moves forward without exposing your business to hidden personnel-related risks.
Practical takeaway: Confirm that your sign contractor’s workers comp policy is active and covers all crew members. Ask for the specific employee names who will be on your job site and verify they’re included in the policy.
How Our Coverage Limits Safeguard Your Investment
A $1 million per occurrence liability limit might sound high until you price out real-world scenarios. If our installation crew accidentally damages the electrical panel during mounting, that could be $5,000 to $15,000. If the sign itself has a defect and causes property damage, add another $20,000. If a customer or employee gets injured by a falling component, medical bills plus legal defense could easily exceed $100,000.
Our aggregate limit of $2 million means that if multiple claims occur during the policy period, we have sufficient coverage for more than one incident. This matters because commercial projects sometimes involve unforeseen complications. Our coverage limits give you confidence that claims will be paid without depleting resources.
We also carry pollution liability and auto coverage for our work vehicles. When our crew arrives in a company truck and parks it safely during installation, that vehicle is insured. If we’re mixing materials or using any sealants near environmentally sensitive areas, that exposure is covered too.
These aren’t theoretical protections. They’re actively managed policies that we’ve established to match the actual risk profile of commercial sign work in Dallas’s climate and environment.
What to do next: When comparing sign contractors, compare their coverage limits directly. A contractor with only $300,000 per occurrence liability is significantly under-insured for commercial projects.
The Permit Process: How Insurance Integrates Into Compliance
Dallas city permits for commercial signage require proof of insurance as part of the approval process. When we submit permit applications for your project, we include our Certificates of Insurance. The city uses this documentation to verify that the installation contractor has adequate protection and bonding. Without it, your permit application faces delays or denial.
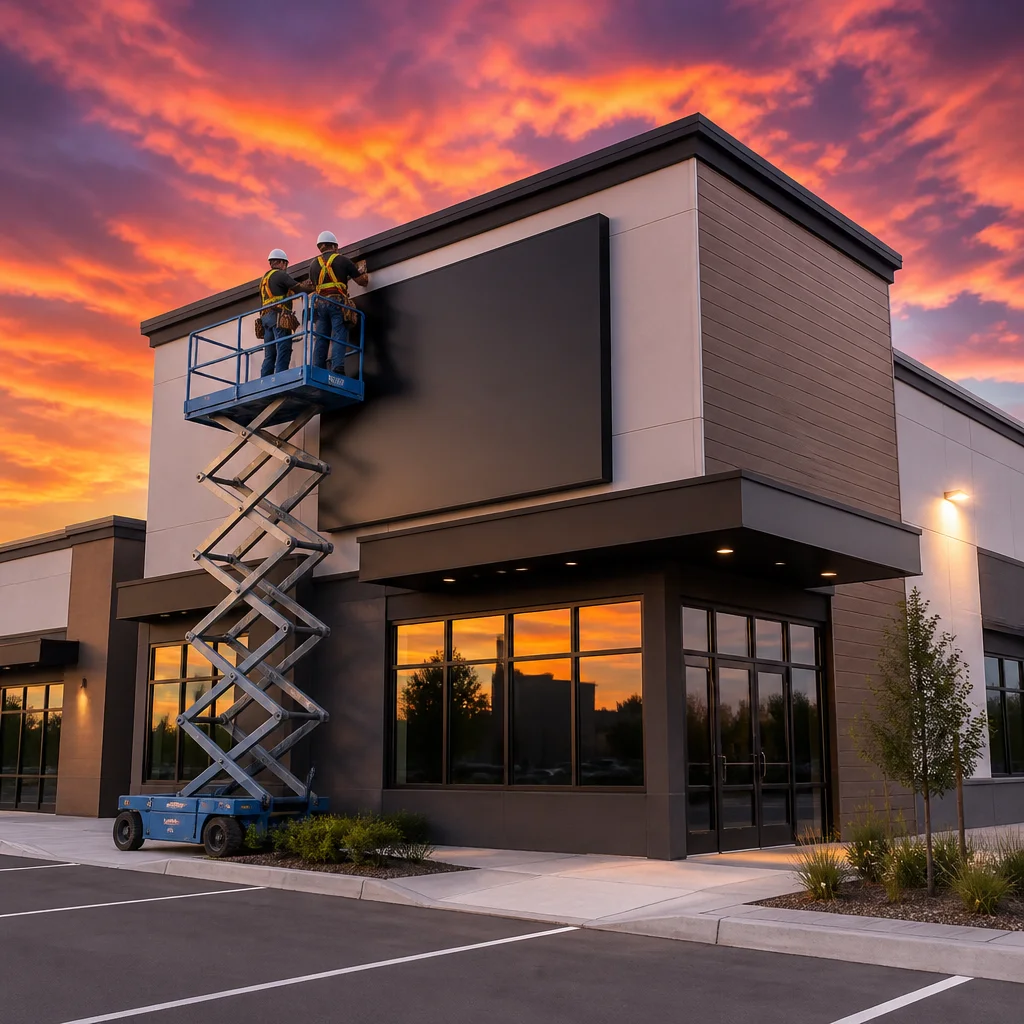
Some business owners try to self-install signage to avoid permit requirements and associated costs. This creates substantial risk. An unpermitted sign installation can result in city fines, demands to remove the installation, and potential liability exposure if anything fails. Our streamlined permits and installation process handles all of this for you.
Insurance documentation also protects your building inspector during their approval walk-through. They know that the contractor performing the work is properly covered and bonded. This gives them confidence in the installation quality and adherence to code.
When we handle your sign project in Dallas, we manage the entire permit workflow. Our insurance information is part of the submitted package, and we coordinate with city departments to ensure compliance. You don’t have to worry about documentation gaps.
Actionable step: If you have an existing sign installation in Dallas that wasn’t permitted, consult with a code compliance specialist now. Addressing it proactively is far cheaper than waiting for the city to discover it.
Why General Contractors Choose Our Verified Coverage
General contractors who oversee multiple subcontractors rely on our proof of insurance to demonstrate to their clients that every team member is properly covered. When a GC can show a property owner or project manager that the sign installation contractor carries full liability, workers comp, and bonding, it simplifies the entire approval process and reduces risk across the project.
We make this easy. We provide certificates of insurance in whatever format your GC needs. We include our agent’s contact details so verification is straightforward. We maintain current coverage year-round and update certificates automatically when policies renew.
GCs also appreciate that we handle our own permitting and compliance. We don’t ask them to obtain permits for us or manage the insurance documentation process. That’s our responsibility, and we take it seriously.
Several of our largest clients are general contractors who’ve worked with us on multi-location sign projects, parking lot signage installations, and facility rebranding initiatives. The consistency of our insurance documentation and permit handling has made us a trusted partner across their portfolios.
Next step: If you’re a general contractor evaluating sign installation partners, request our full Certificate of Insurance and talk directly with our insurance broker to verify active coverage.
Documentation and Peace of Mind: What You Receive
When you hire us for your sign installation, you’ll receive:
- An executed Certificate of Insurance naming your business as additional insured (30 days before work starts)
- Our broker’s contact information for independent verification
- A signed contract that clearly outlines our insurance obligations
- A project timeline that includes our safety protocols and crew credentials
- Photographic documentation of pre-installation conditions at your site
- Post-installation inspection records and signed approval forms
All of this documentation goes into a project file that we maintain. If questions arise months or years later about the installation process, we have a complete record of what was done, who did it, and what coverage was in place.
We also provide detailed invoicing that includes itemized labor, materials, and warranty components. This documentation becomes part of your business records and is useful for accounting, insurance claims, and facility audits.
What to do next: Create a dedicated file folder (digital or physical) for all signage project documentation. Store your Certificate of Insurance, contract, and installation photos together. This becomes invaluable reference material if you ever need to prove that installation was performed by a licensed, insured professional.
Our 5-Year Warranty Works Hand-in-Hand With Insurance
Our installation liability insurance doesn’t replace our warranty; they work together to protect you. The warranty covers defects in materials and workmanship for five years after installation. Our insurance covers liability claims and injury-related incidents that occur during and after installation.
If a sign component fails because of a manufacturing defect within the warranty period, we repair or replace it. If that failure damages something else on your property, our liability insurance covers it. You’re never out of pocket.
This dual-layer protection is rare in the sign industry. Many contractors offer minimal warranties and minimal insurance. We’ve built our business on the principle that when we install something on your property, we take long-term responsibility for it.
The warranty is documented at the time of installation and provided in writing. Our insurance remains current throughout the warranty period. Five years of protection gives you genuine peace of mind.
Getting Started: Requesting Your Proof of Coverage
If you’re ready to move forward with a sign project, here’s exactly what to ask for:
- Request a detailed quote that includes labor, materials, design, and permitting
- Ask for our Certificate of Insurance to be provided with the quote
- Confirm the certificate shows your business name as additional insured
- Ask questions about our coverage limits and what incidents are protected
- Review the certificate with your insurance broker if you want independent verification
- Once you’re satisfied, sign the contract and we’ll schedule the installation
The entire process is straightforward, and we’ve streamlined it to take the complexity out of your decision. You get a professional sign installation from a team that’s fully licensed, insured, bonded, and committed to your satisfaction.
We’ve been serving Dallas business owners and general contractors for years, and our track record speaks for itself. Every project includes proof of insurance, every installation follows code requirements, and every client receives the documentation they need to protect their business.
Contact us today to request a quote and certificate of insurance. We’ll have everything to you within 24 business hours.
Contact us today for a FREE Estimate
Frequently Asked Questions (FAQ)
What insurance coverage do you carry for sign installation projects?
We carry comprehensive general liability insurance and workers compensation coverage on all installation jobs. Our policies protect both your business and our team, with liability limits that safeguard your property and assets throughout the installation process. We provide proof of our current coverage upon request before any work begins on your project.
Why should I request proof of insurance before hiring a sign company?
Proof of insurance protects you from liability if an accident occurs during installation on your property. Without verification that we’re properly bonded and insured, you could face unexpected costs or legal complications. We make it simple by providing all documentation upfront so you can verify our coverage meets your requirements and your general contractor’s standards.
How does your insurance coverage work with the 5-year warranty you offer?
Our warranty and insurance work together to give you complete protection for your investment. The warranty covers defects in materials and workmanship, while our liability coverage protects against installation-related incidents. This dual approach means you’re covered from day one through the full warranty period, backed by both our commitment and our bonded coverage.